
When you invest in a private equity fund or a real estate deal, one document quietly determines how much money you actually take home: the distribution waterfall. It defines the order in which cash flows back to investors and sponsors, and it can make the difference between a strong net return and a disappointing one—even when the underlying deal performs exactly the same.
Below, we break down how waterfalls work, why the structure matters, and what to look for before you sign.
What Is a Distribution Waterfall—and Why Does It Exist?
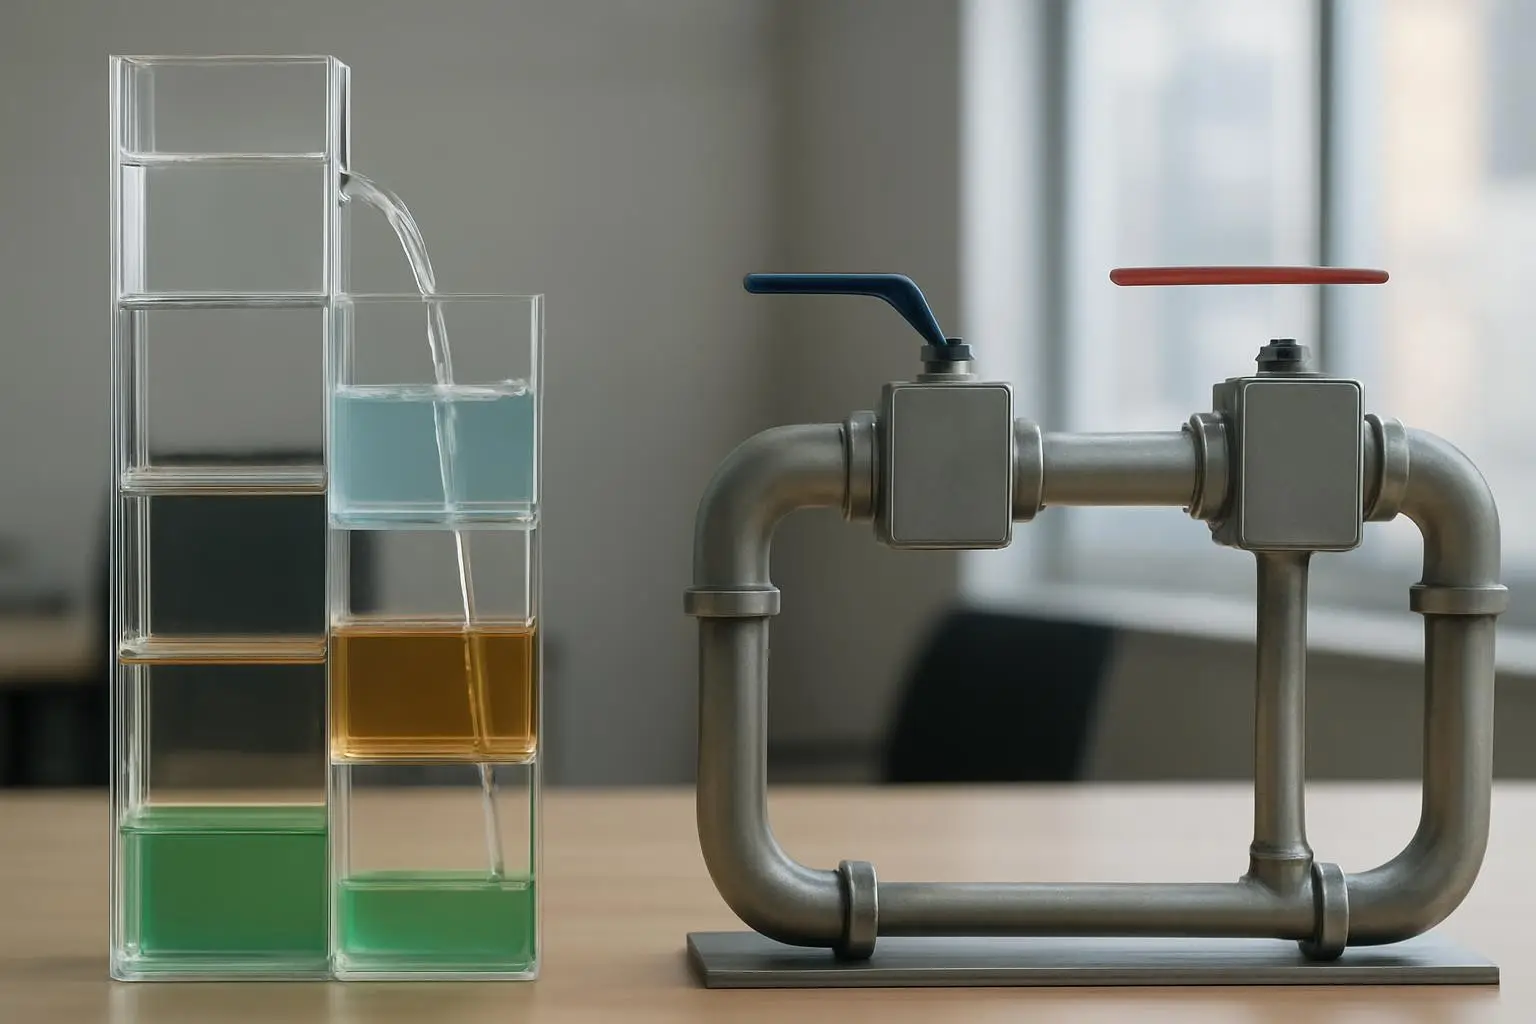
A distribution waterfall is a set of rules that dictates the order in which profits from an investment are paid out. Think of it as a series of buckets: cash fills the first bucket completely before spilling into the next.
The structure exists to align interests between two parties. Limited partners (LPs) provide the capital, while general partners (GPs) manage the investment. The waterfall protects LPs by returning their money first, then rewards GPs with a larger share of profits once certain performance targets are met.
Private equity vs. real estate: the same idea, different deal stack
The core logic is identical across both asset classes, but the mechanics differ. In private equity, the waterfall usually operates at the fund level, pooling many portfolio companies together.
In real estate, waterfalls often operate deal by deal, since each property generates its own cash flow and eventual sale proceeds. Real estate structures also tend to include multiple tiers with escalating profit splits tied to specific return hurdles.
How Do Distributions Work in a Typical Waterfall Structure?
A standard waterfall moves through four sequential stages. Cash flows fill each tier before moving to the next.
Return of capital, preferred return/hurdle, catch-up, then carry
First comes the return of capital. LPs receive their invested principal back before anyone else takes a profit.
Next is the preferred return, sometimes called the hurdle. LPs earn a minimum annual return—often 6% to 8%—before the GP participates in profits.
Then comes the catch-up. In this tier, the GP receives a disproportionate share of profits to “catch up” to their agreed split, effectively balancing the preferred return already paid to LPs.
Finally, remaining profits are split according to carried interest, or carry. A common arrangement is 80/20, where LPs keep 80% and the GP earns 20% of profits above the hurdle.
European vs. American Waterfalls: When Does Carry Get Paid?
The single biggest structural difference lies in timing. European and American waterfalls determine when the GP can start collecting carry.
How up-deal and down-deal outcomes change the timing
In a European (whole-fund) waterfall, the GP earns carry only after LPs receive all their capital back plus the preferred return across the entire fund. This approach favors LPs, since strong early deals cannot pay carry until weaker later deals are accounted for.
In an American (deal-by-deal) waterfall, the GP can earn carry on individual profitable deals before the whole fund returns capital. As a result, GPs receive carry sooner on up-deals.
However, this creates risk if later down-deals underperform. To address it, American structures typically include a clawback provision, which requires the GP to return excess carry if the fund ultimately falls short of its targets.
Key Waterfall Terms That Drive Investor Returns
A handful of terms carry outsized weight in determining your net outcome. Understanding each one helps you compare deals accurately.
Hurdle rate, preferred return, carry, catch-up, and loss sharing
The hurdle rate is the minimum return threshold the investment must clear before the GP shares in profits. A higher hurdle generally favors LPs.
The preferred return is the priority return paid to LPs, usually expressed as an annual percentage. It can be compounding or simple, which meaningfully affects the total.
Carried interest is the GP’s share of profits above the hurdle. The catch-up determines how quickly the GP reaches its full carry percentage after the preferred return is paid.
Finally, loss sharing defines how losses are allocated. In some structures, the GP absorbs first losses; in others, losses flow to LPs after their capital is at risk.
Common Waterfall Variations Investors Should Watch For
No two waterfalls are exactly alike. Variations in structure can shift returns significantly, so it pays to read closely.
Deal-level vs. fund-level mechanics and how “first loss” structures work
As noted, deal-level waterfalls calculate distributions on each individual investment, while fund-level waterfalls aggregate all investments before paying carry. Deal-level structures accelerate GP compensation; fund-level structures delay it.
A “first loss” structure requires one party—often the GP or a subordinate tranche—to absorb initial losses before other investors are affected. This provides a cushion for senior LPs and signals the sponsor’s confidence in the deal.
Watch also for multiple hurdle tiers, where profit splits escalate as returns rise. For example, an 80/20 split might shift to 70/30 above a second hurdle and 60/40 above a third.
How to Evaluate a Proposed Distribution Waterfall (LP Checklist)
Before committing capital, review the waterfall terms methodically. The details live in the limited partnership agreement (LPA) or operating agreement.
What to review in the LPA or operating agreement before signing
Start with the sequence. Confirm the exact order of return of capital, preferred return, catch-up, and carry, and verify whether the structure is European or American.
Next, check the numbers. Note the hurdle rate, whether the preferred return compounds, the carry percentage, and how the catch-up is calculated.
Then, examine the protections. Look for a clawback provision, loss-sharing terms, and any first-loss cushion that affects your downside.
Finally, model the outcomes. Run the waterfall under low, base, and high performance scenarios to see how your net return changes. This step often reveals whether a structure genuinely favors LPs or quietly tilts toward the GP.
FAQ
What is a distribution waterfall structure in finance?
A waterfall structure is a method for allocating payments or proceeds in a predetermined order. It is used to show how money flows between different parties or claim types as funds become available.
How does a waterfall structure work when distributing payments?
Distributions are typically made sequentially: cash is directed to one group or obligation first, then the remainder flows to the next level. The order and rules are set in advance in the contract terms.
Why use a waterfall structure for distributions?
The purpose is to clarify and enforce a priority-based distribution of cash flows—so participants understand who gets paid first and how proceeds are allocated under different performance scenarios.
What is a “waterfall structure bond”?
A “waterfall structure bond” generally refers to a bond whose payment stream follows a waterfall allocation method, meaning bondholders’ cash flows are distributed according to priority rules rather than a single uniform approach.
What determines how funds are allocated in a waterfall bond?
Allocation is governed by the bond’s underlying terms—such as the priority or order of payments among different classes or obligations—which are specified in the bond documentation.
Are there different types of distribution waterfall structures?
Yes. Waterfall structures can vary by product and by how priorities are defined. The common feature is an ordered distribution of proceeds, even though the details differ.
Where else is a distribution waterfall structure used besides bonds?
Besides bonds, waterfall-style allocation is used anywhere priority-based distribution rules are needed—such as in private equity and other arrangements involving multiple stakeholders with different payment priorities.