
Structured finance brings capital markets techniques into real estate, allowing complex properties and portfolios to be financed through layered, customized debt and equity instruments. Rather than relying on a single loan, these deals divide risk and return among multiple parties, each with different appetites and priorities. For investors, understanding how these structures work is essential to evaluating where their money sits, what protections they hold, and what returns they can realistically expect.
What Is Structured Finance in Real Estate?
Structured finance refers to a set of financing techniques that pool real estate assets or cash flows and redistribute them into customized instruments. Unlike a straightforward mortgage, these arrangements use special purpose vehicles, layered capital, and contractual rules to allocate risk precisely.
In practice, this means a single property or a portfolio of properties can support several distinct investments. Each investment carries its own risk level, priority of payment, and expected yield.
The goal is flexibility. By structuring cash flows carefully, sponsors can match different pieces of a deal to different investors, from conservative lenders to opportunistic equity players.
How Do Structured Finance Deals Work? Mechanics and Flow
Most structured deals begin with a special purpose vehicle (SPV) that holds the underlying real estate assets. This entity isolates the assets legally, separating them from the sponsor’s other obligations.
Next, the SPV issues securities or loans backed by the property’s income. Rent, mortgage payments, or sale proceeds flow into the structure and are distributed according to a predefined set of rules, often called the “waterfall.”
The waterfall determines who gets paid first. Senior investors receive their share before subordinate investors, and expenses or reserves may come off the top.
Finally, the structure includes triggers and covenants. If performance falls below certain thresholds, cash may be redirected to protect senior positions, changing how and when junior investors are paid.
What Is Tranching, and How Does It Change Risk and Returns?
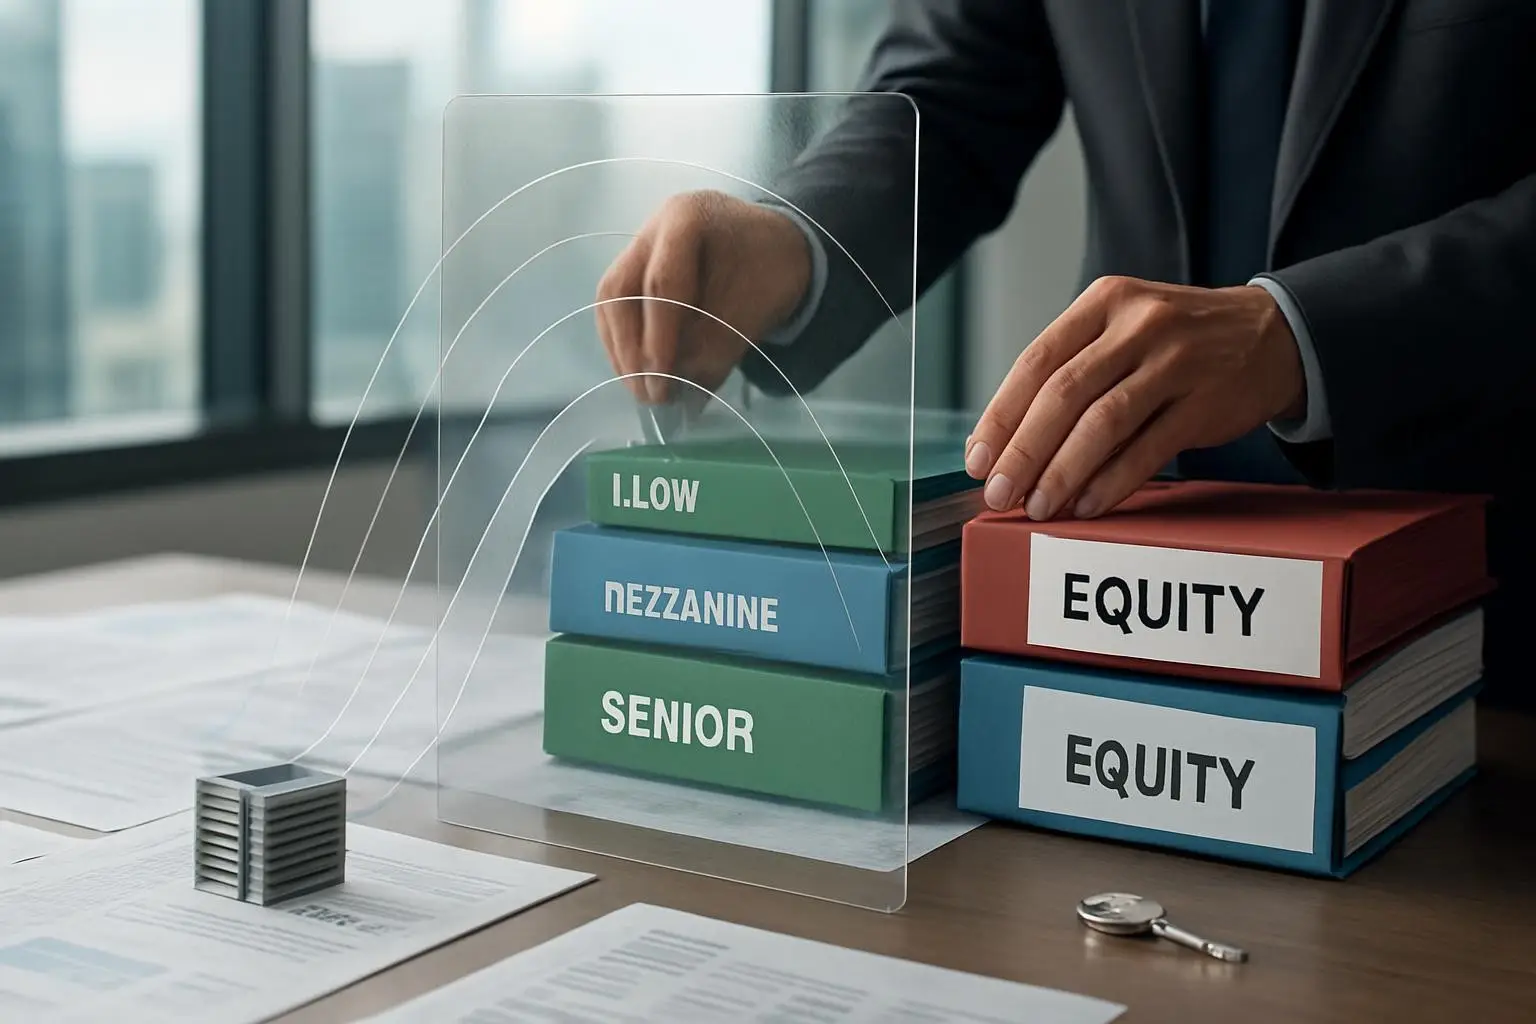
Tranching is the process of slicing a deal’s capital into layers, each with a different claim on cash flows. The senior tranche sits at the top, followed by mezzanine tranches, and finally the equity or junior tranche at the bottom.
Senior tranches are repaid first, so they carry the lowest risk and the lowest return. Because they absorb losses last, they typically earn an investment-grade profile.
Junior and equity tranches, by contrast, absorb losses first. In exchange for this higher risk, they are positioned to capture higher returns when the property performs well.
Therefore, tranching allows one asset to serve many investor types. A pension fund might buy the senior tranche for stability, while an opportunistic fund takes the equity tranche for upside potential.
Structured Real Estate Finance vs. Traditional Lending: Key Differences
Traditional lending usually involves a single lender issuing one loan secured by a property. The borrower repays principal and interest on fixed terms, and the lender bears the full credit risk.
Structured finance, on the other hand, divides risk among multiple parties. Instead of one loan, you have layered instruments with different priorities and returns.
Another difference is customization. Traditional loans follow relatively standard terms, while structured deals are tailored through waterfalls, covenants, and tranching.
Finally, liquidity can differ. Some structured instruments are designed to be sold or securitized, whereas a traditional mortgage often stays on a single lender’s books.
Who Are the Main Parties in Structured Real Estate Finance?
The sponsor, or originator, assembles the deal and often retains an equity stake. This party identifies the assets, structures the financing, and manages execution.
Investors come next, spread across tranches. Senior lenders prioritize safety, mezzanine investors seek a balance, and equity investors pursue the highest returns.
Servicers manage the day-to-day cash flows, collecting payments and distributing them according to the waterfall. Special servicers may step in if loans become distressed.
Additionally, rating agencies, legal counsel, and trustees play supporting roles. They assess risk, document terms, and enforce the rules that govern the structure.
What Are the Benefits of Structured Finance for Real Estate Investors?
One key benefit is access. Structured finance lets investors choose a risk level that fits their mandate, whether conservative or aggressive.
It also enables larger and more complex projects. By pooling capital and layering risk, sponsors can fund assets that a single lender might avoid.
Diversification is another advantage. Pooling multiple properties can spread exposure across locations and asset types, reducing reliance on any single property.
Finally, tranching provides tailored returns. Investors can target specific yields and protections rather than accepting a one-size-fits-all loan structure.
What Trade-Offs Should Investors Watch in Structured Real Estate Finance?
Complexity is the first trade-off. These deals involve layered documents and rules that require careful review to understand where risk truly sits.
Transparency can also be a challenge. When assets are pooled, it may be harder to assess the quality of each underlying property.
Liquidity varies as well. Some tranches are difficult to sell, especially subordinate positions during periods of market stress.
Moreover, junior investors face concentrated risk. Because they absorb losses first, a modest decline in performance can significantly reduce their returns.
Mini Case Studies: Structured Real Estate Finance in Practice
Consider a sponsor financing a $100 million office portfolio. They structure a $60 million senior tranche, a $20 million mezzanine tranche, and $20 million in equity. Rental income flows first to the senior lenders, then to mezzanine, and finally to equity.
In a strong market, the properties generate steady rent, and all tranches are paid in full. The equity holders capture the surplus, earning the highest return.
Now imagine occupancy drops sharply. Cash flow narrows, and the waterfall directs payments to the senior tranche first. The equity holders absorb the shortfall, and their returns decline before senior lenders feel any impact.
In another scenario, a mixed-use development uses mezzanine financing to bridge a funding gap. The mezzanine investor earns a higher rate than the senior lender but accepts a subordinate claim, illustrating the risk-return balance of middle tranches.
Glossary: Common Terms in Structured Real Estate Finance
Special Purpose Vehicle (SPV): A legal entity created to hold assets and isolate them from the sponsor’s other obligations.
Tranche: A layer of a deal’s capital with a defined priority of payment and risk level.
Waterfall: The set of rules determining the order in which cash flows are distributed to investors.
Mezzanine: A middle layer of financing that sits between senior debt and equity, carrying moderate risk and return.
Covenant: A contractual condition that the borrower or structure must maintain, often tied to performance triggers.
Subordination: The ranking of a claim below another, meaning it absorbs losses first and is repaid later.
FAQ: Structured Finance and Tranching in Real Estate
Is structured finance only for large institutions? While large players dominate, smaller investors can access these structures through funds or syndicated positions.
Which tranche is safest? The senior tranche carries the lowest risk because it is repaid first and absorbs losses last.
How is tranching different from simple debt and equity? Tranching adds multiple layers between debt and equity, each with its own risk and return profile, rather than just two positions.
What happens if a property underperforms? The waterfall redirects cash to senior positions, so junior and equity investors feel the impact first.
Are structured deals liquid? Liquidity varies by tranche. Senior positions tend to be more marketable, while junior tranches can be harder to sell.
Real Estate Finance Modeling Questions for Structured Finance Deals
When modeling these deals, start with the cash flow projections. How reliable is the underlying rental income, and what assumptions drive it?
Next, examine the waterfall logic. Does your model correctly sequence payments across each tranche under both base and stress scenarios?
Consider the triggers and covenants. How does your model respond when performance thresholds are breached and cash is redirected?
Finally, test sensitivity. How do returns for each tranche change when occupancy, interest rates, or exit values shift? Stress testing reveals where the structure holds and where it breaks.